Written by Pro Value Contracting | Published on July 2025
Most standard homeowner insurance policies in California cover sudden and accidental water damage, but they exclude flooding, groundwater intrusion, and damage caused by neglected maintenance. Knowing the difference could mean the gap between a full payout and a denied claim. This guide walks San Diego homeowners through the most common water damage scenarios, what insurance typically covers, and how to protect yourself when a claim gets complicated.
Understand What Standard Homeowner Policies Actually Cover
California homeowner insurance policies follow a principle called “sudden and accidental” coverage. If water damage happens quickly and unexpectedly, it is usually covered. If it develops slowly over time, it is usually not.
Here are the most common types of water damage that standard policies typically cover:
- Burst pipes caused by freezing temperatures or sudden pressure failure
- Water damage from an overflowing appliance like a dishwasher or washing machine
- Water intrusion caused by a covered roof event, such as wind or hail damage
- Accidental discharge from a plumbing fixture
- Water damage resulting from firefighting efforts after a covered fire
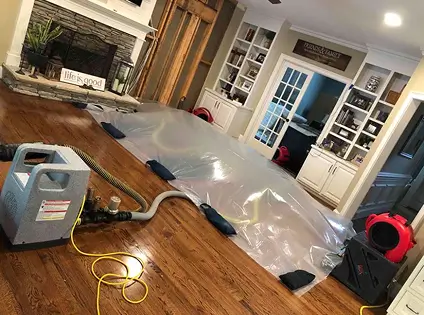
These are the scenarios where filing a claim is usually straightforward. Document everything immediately, including photos and timestamps, before any cleanup begins.
Pro Value Contracting works with San Diego homeowners to document damage correctly from the start, which makes the claims process much smoother with your insurer.
Identify Water Damage Types That Are Typically Not Covered
Many homeowners in San Diego are surprised to learn how many common water damage situations fall outside standard policy coverage. Insurance companies draw a hard line between sudden events and gradual damage.
| Water Damage Type | Covered by Standard Policy? | Separate Coverage Available? |
|---|---|---|
| Burst pipe (sudden) | Yes | N/A |
| Slow pipe leak over months | No | No |
| Flood from heavy rain or storm surge | No | Yes, via NFIP or private flood insurance |
| Sewer backup or drain overflow | No | Yes, via endorsement add-on |
| Groundwater or foundation seepage | No | Rarely available |
| Appliance leak caught early | Depends on timeline | Possibly via home warranty |
| Mold from undetected moisture | Limited or no | Sometimes via mold endorsement |
California insurance law does not require insurers to cover gradual damage. This is one reason why routine inspections and early leak detection matter so much for homeowners.
Explore How Flood Insurance Works in San Diego, CA
Standard homeowner policies do not cover flooding. In San Diego, this is a critical gap because heavy winter rains, coastal storm surges, and flash flooding in canyon areas all pose real risks to residential properties.
Flood insurance in California is available through two main channels. The National Flood Insurance Program (NFIP), managed by FEMA, is the most common option. Private flood insurance carriers offer an alternative that sometimes provides higher coverage limits and broader definitions of flood damage.
Key facts about flood insurance in San Diego:
- NFIP policies typically have a 30-day waiting period before coverage begins
- The maximum NFIP building coverage is $250,000 for residential structures
- Contents coverage under NFIP is capped at $100,000 and sold separately
- San Diego County includes both low-risk and high-risk flood zones, so your premium depends on your specific address
- Private flood policies may cover finished basements, temporary housing costs, and higher value properties that exceed NFIP limits
You can look up your property’s flood zone designation using FEMA’s Flood Map Service Center at msc.fema.gov. Many San Diego neighborhoods near Mission Valley, El Cajon, and coastal areas carry elevated flood risk.
Compare Sewer Backup and Water Damage Endorsements
Sewer backup is one of the most common and costly water damage events that standard policies exclude. When a city sewer line backs up into your home, the resulting damage can cost between $3,000 and $15,000 or more depending on how far the water spreads.
The good news is that sewer backup coverage is available as an endorsement, or add-on, to most California homeowner policies. The annual cost is typically between $50 and $250 depending on your insurer and coverage limits.
| Endorsement Type | What It Covers | Typical Annual Cost | Coverage Limit Range |
|---|---|---|---|
| Sewer and Drain Backup | Sewage overflow into home, drain backups | $50 to $250 | $5,000 to $25,000 |
| Water Backup and Sump Overflow | Failed sump pump, backed up drains | $75 to $200 | $5,000 to $25,000 |
| Service Line Coverage | Breaks in water lines from street to home | $25 to $100 | $10,000 to $50,000 |
| Mold Endorsement | Mold remediation after a covered event | $50 to $150 | $5,000 to $15,000 |
These endorsements are inexpensive relative to the cost of a major sewer backup claim. Talk to your insurance agent to confirm which ones are available under your current policy in California.
Recognize How Insurance Companies Define Gradual Damage in California
California courts and insurance regulators have upheld the exclusion of gradual water damage in most homeowner policy disputes. Insurers define gradual damage as any damage that occurred over a period of weeks, months, or years rather than all at once.
Common examples of gradual damage that California insurers deny include a slow leak behind a wall, a roof flashing drip that worsened over two seasons, and a corroded pipe fitting that seeped for months before failing completely.
The challenge is that many leaks are hidden. You may not know a pipe has been dripping behind drywall until the damage is already significant. In these cases, the insurer may deny coverage citing homeowner negligence or failure to maintain the property.
This is where working with a restoration company like Pro Value Contracting early in the process matters. We can help document when damage was discovered versus when it likely started, which is information your public adjuster or attorney may use if a claim is disputed.
Know Your Rights as a California Homeowner During a Water Damage Claim
California has some of the strongest insurance consumer protections in the country. The California Department of Insurance (CDI) enforces rules that protect policyholders during the claims process.
Here is what California law requires of your insurer after you file a water damage claim:
- Acknowledge your claim within 15 calendar days of receiving notice
- Accept or deny your claim within 40 calendar days of receiving proof of loss
- Pay undisputed amounts within 30 calendar days of reaching an agreement
- Provide a written explanation for any denial or partial payment
- Not misrepresent policy provisions or coverage when explaining a denial
If your insurer is delaying, lowballing, or denying a valid claim, you can file a complaint with the CDI at insurance.ca.gov. California also allows you to hire a public adjuster to negotiate on your behalf.
San Diego homeowners should keep copies of all correspondence with their insurer, including emails and phone call logs. Detailed records make it much easier to escalate if a claim is being mishandled.
FAQs on Water Damage Insurance Coverage in California
Does homeowner insurance cover water damage from a leaking roof in California?
It depends on the cause of the roof damage. If a storm or wind event caused the roof to leak, the resulting water damage is typically covered. If the roof was leaking due to age or lack of maintenance, the claim will likely be denied under the gradual damage exclusion.
Will insurance pay for mold removal after a water damage event in San Diego?
Standard policies offer limited mold coverage, often capped at $5,000 to $10,000 and only when the mold resulted from a covered water event. You can purchase a mold endorsement for broader protection. San Diego’s humid coastal climate makes mold a real concern after any water intrusion.
How long do I have to file a water damage claim in California?
California law generally requires homeowners to report claims promptly after discovering damage. Most policies have a one-year deadline to file a lawsuit over a denied claim, but waiting even a few days to report damage can give insurers grounds to dispute coverage. Report the damage as soon as you find it.
Does insurance cover water damage from an overflowing toilet or bathtub?
Yes, if the overflow was sudden and accidental, most standard homeowner policies will cover the resulting water damage. However, if the toilet overflowed due to a known clog that was ignored, the insurer may deny the claim citing negligence. Always address plumbing issues quickly.
What is the difference between water damage and flood damage for insurance purposes?
Insurers define flood damage as water that originates from outside the home, such as rising rivers, storm surge, or heavy rain runoff. Water damage refers to water that originates from within the home or from above, like a burst pipe. Flood damage requires a separate flood insurance policy.
Can I get reimbursed for a hotel stay if water damage makes my San Diego home uninhabitable?
Yes, most homeowner policies include Additional Living Expenses (ALE) or Loss of Use coverage. This pays for temporary housing, meals, and other costs while your home is being repaired after a covered event. Review your policy’s ALE limit, as it varies by carrier and coverage level.
Wrap Up and Next Steps
Water damage insurance in California is more nuanced than most homeowners realize. Knowing which types of damage are covered, which require separate policies or endorsements, and what your rights are during a claim can protect you from costly surprises.
If your San Diego home has experienced water damage, acting fast is critical. The longer water sits, the more likely your insurer is to question the timeline of events and the more likely mold is to develop.
Pro Value Contracting is here to help San Diego homeowners respond quickly, document damage thoroughly, and restore their homes the right way. Call us today at (888) 508-6580 to schedule an assessment or get a free quote on water damage restoration services.